Posts

Earn Too Much for a Roth IRA? How the 2026 Income Phase-Outs Shrink — or Erase — Your Contribution

Image
A raise, a bonus, or a strong year for a side business can do something no one warns you about: it can quietly disqualify your Roth IRA contribution. Not because you did anything wrong, but because the IRS phases out direct Roth IRA contributions on income. Earn inside the band and your contribution shrinks. Earn above it and you cannot contribute directly at all — even if you have the money ready and every other rule checks out. This post is about that income test: where the lines sit for 2026, what happens when you cross them, and the three routes that still work when you earn too much. The income test comes first Most Roth IRA explanations start with how much you can put in. Start with whether you are allowed to put anything in directly, because the income answer changes everything else. The test runs on modified adjusted gross income (MAGI) — roughly your adjusted gross income with certain deductions added back — and it applies per filing status: Filing status Full direct con...

How to Check Your Exact January 2027 Social Security Payment in my Social Security (and What to Do If It Looks Wrong)

Image
How to Check Your Exact January 2027 Social Security Payment in my Social Security (and What to Do If It Looks Wrong) By Daniel Kim You have probably heard the headline: Social Security benefits rise 3.6 percent for January 2027. That headline does not tell you your number. Your January payment depends on your own benefit, your own deductions, and whether you receive Social Security or Supplemental Security Income. This post is a step-by-step check you can do in your my Social Security account, so you know exactly what to expect and what to do if the number looks wrong. This post does not repeat the COLA news. It tells you how to verify your own payment. If you want the COLA calculation itself, the Social Security Administration's COLA page is linked in Sources below. Step 1: Know which payment you are checking Social Security and SSI follow different timing for January 2027. Social Security benefits increase by 3.6 percent beginning with the December 2026 benefits, which ar...

Lump Sum Cash: How $10,000 Can Lose Value If It Just Sits

Image
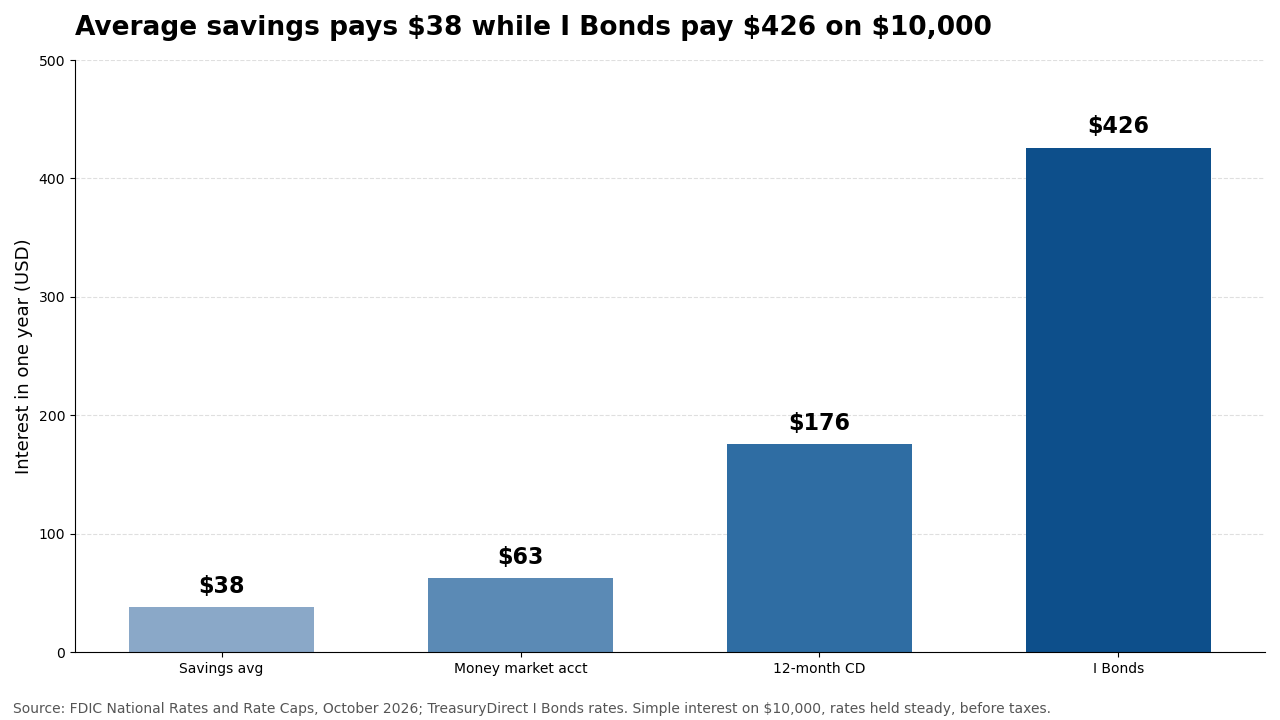
You just received $10,000 you did not expect: a bonus, a tax refund, a small windfall. The bottom line is simple, and it comes before any product name. Put money you owe soon in checking, pay down your highest-APR debt, keep a buffer you can reach any day, and only then lock money away for yield. The order matters more than the exact split, because each step protects the next one. Here is the key figure. At the national average savings rate of 0.38% (FDIC, October 19, 2026), $10,000 earns $38 in a year. At the current Series I savings bond composite rate of 4.26% (TreasuryDirect, for bonds issued May 1 to October 31, 2026), the same $10,000 earns $426 in a year if the rate holds steady. The gap is $388, before taxes, on the same sum. Leaving the whole amount in an average account does not feel like a decision, but the arithmetic treats it as one. This post uses $10,000 as the worked example throughout, because the FDIC publishes its national averages on deposit tiers that include $10...

Mortgage Rates: The Simple Guide to Refi Rates on Oct. 28

Image
The 30-year fixed mortgage rate for October 28, 2026, had not been published yet (Freddie Mac publishes its weekly survey on Thursdays), so this post uses the latest available weekly average as its benchmark; the series is published by the Federal Reserve Economic Data (FRED) as MORTGAGE30US . You hold a mortgage because you need a roof, not because you want to trade financial instruments. Yet the rate on your next refinance is determined by forces far removed from your kitchen table: the Federal Reserve’s balance sheet size, the yield on 10-year Treasuries, and the supply of mortgage-backed securities. When the Fed sells bonds (quantitative tightening), it reduces liquidity in the mortgage market, pushing yields up. When the yield on 10-year Treasuries rises, lenders demand a higher rate to compensate for the risk of holding long-term debt. A 100-basis-point shift in the 10-year yield typically moves the 30-year mortgage rate by roughly 75 to 100 basis points (0.75 to 1.00 percentag...

Your Bank Account Is Insured to $250,000 — Until It Isn't: The 3 Rules That Decide What Actually Comes Back

Image
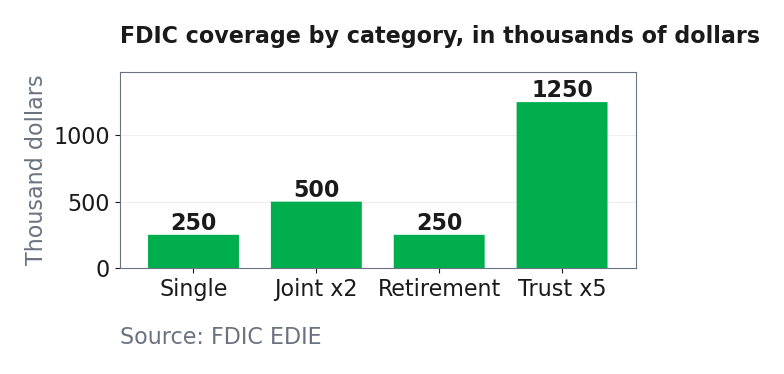
If your bank failed tomorrow, how much of your money would come back? Most people answer with one number: $250,000. That number is real, but it is not the whole answer. The Federal Deposit Insurance Corporation does not insure $250,000 per account. It insures $250,000 per depositor, per insured bank, for each account ownership category. Those three extra words — per depositor, per bank, per category — are where money is either protected or left exposed, and they are the reason two people with the same balance at the same bank can have very different outcomes. This post explains the rule in plain language, shows the arithmetic with worked examples, and gives you a 10-minute check you can run on your own accounts. All of the coverage figures below come from the FDIC's own estimator guidance. Where this post uses an example balance, it says so plainly: the example is arithmetic, not a claim about any real person's account. $250,000 Per depositor, per insured bank, per ownership ...

Headlines Say Housing Is Heating Up — Your Wallet Says Otherwise

Image
If you saw a housing headline this week and felt a flicker of hope, you are not alone. A national price index went up, and up is supposed to be good news. But a headline is not a wallet. Your wallet cares about what a home costs to buy, what it costs to borrow for, and whether anyone is actually buying. Put those three things side by side, using the latest official reports, and the story changes. Prices are higher than a year ago on paper and lower after inflation. Sales are still running behind last year. Borrowing costs are still high, even after a small weekly dip. That is not a market heating up. That is a market stuck between high prices and high rates, with buyers and sellers both waiting for the other side to blink first. This post does one simple thing: it lines up the price, sales, and rate reports so you can see them together, instead of one headline at a time. All of the figures below come from the official releases themselves, linked at the end. Where a figure is uncertain...